- Name:
- Marco Kisic
- Title:
- Head of ESG Research, Nordea Equities
Denne siden findes ikke på norsk
Bli værende på denne siden | Fortsett til en lignende side på norskMarco Kisic
3 min to read
Nordic companies remain firmly committed to addressing climate change and are delivering well on their Scope 1 and 2 emissions. However, our annual review of climate targets and progress across a universe of approximately 330 Nordic companies reveals a persistent gap between ambition and delivery on Scope 3 emissions.
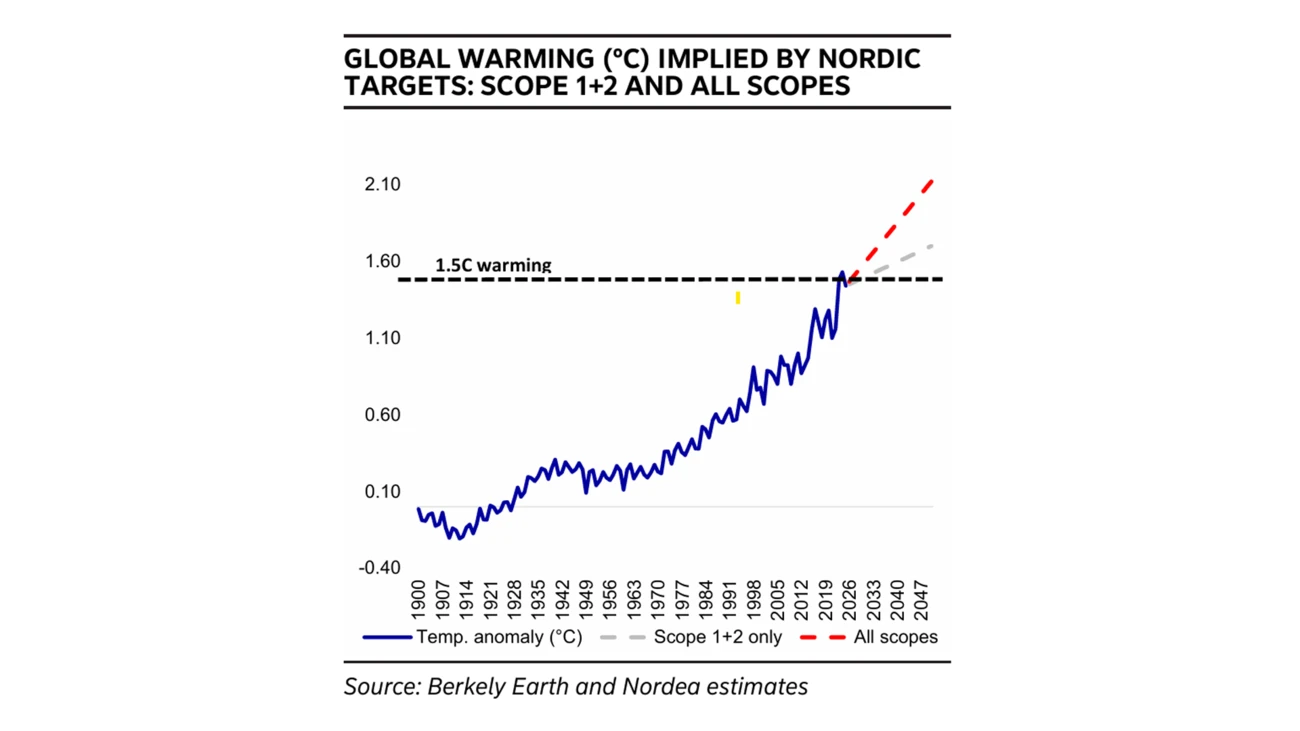
With global warming averaging 1.48°C in 2023–25, crossing the 1.5°C threshold is now widely assessed as unavoidable (UN EP, 2026). Beyond that level, climate risks and impacts will reach a dangerous intensity, and the focus must shift to minimising peak temperatures and eventually bringing them back down.
Our annual review of Nordic companies' emission targets shows that, beyond a few exceptions, commitment to the climate remains firm. When assessing the temperature rise implied by their targets, however, we drop 1.5°C as our main reference scenario and estimate that even full delivery implies 1.7°C global warming for Scope 1 and 2. This changes if we add in Scope 3, which implies that temperatures could reach 2.0-2.1°C. In our view, this calls for increased urgency and ambition from leading companies.
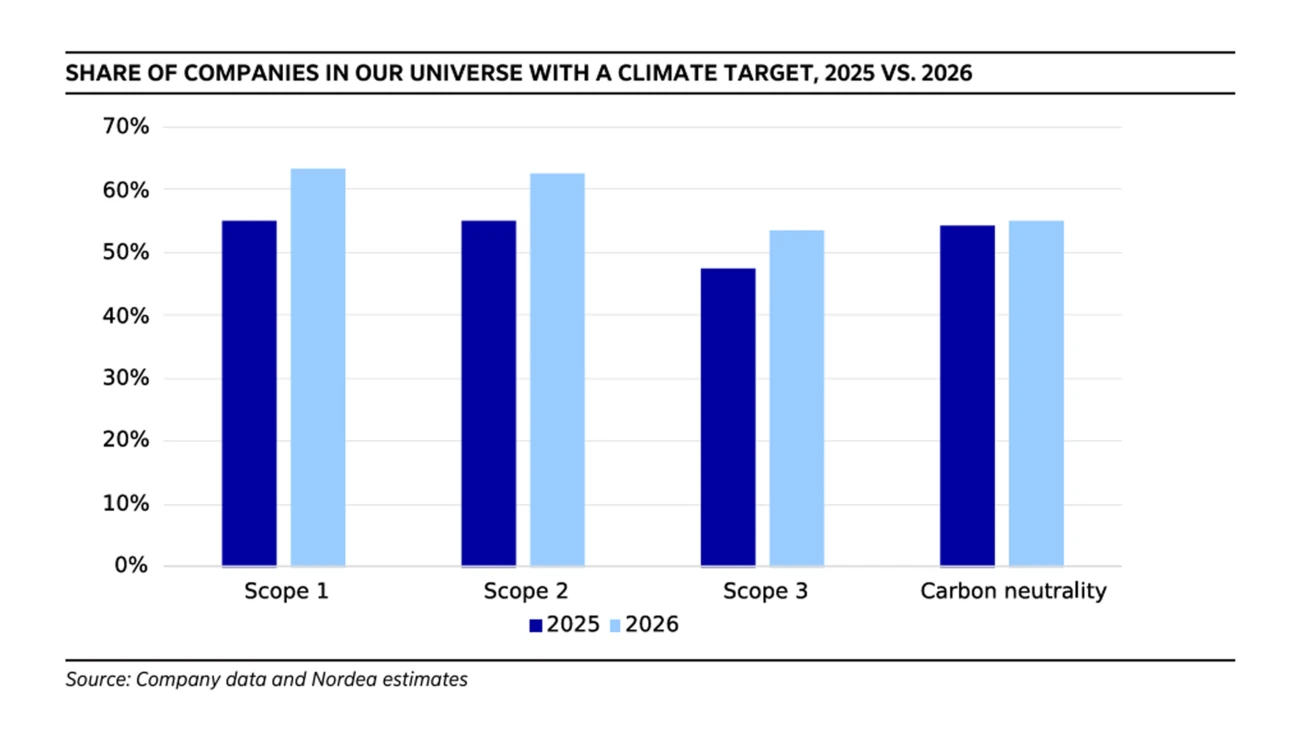
On the positive side, Nordic companies are broadly maintaining their climate commitments. On average, more companies have climate targets than last year (63% for Scope 1 and 2 versus 55% in 2025, and 54% for Scope 3 versus 47%).
Delivery on Scope 1 and 2 targets is progressing well, with the majority of emissions assessed as on track. Scope 1 and 2 emissions of the companies in our coverage universe declined by 3% year-on-year in 2025 and are down 34% since 2020. Although Scope 1 is somewhat flatlining, Scope 2 can carry large decarbonisation weight for a while longer.
Scope 3 emissions account for 97% of universe emissions and remain the key challenge. Absolute Scope 3 was flat year-on-year, and we assess that half of our universe Scope 3 is not on track with targets. Barring a few sectors and despite all of its shortcomings, we expect Scope 3 to become the main focus of decarbonisation strategies in the years ahead.
Source: Company data and Nordea estimates
From February 2027, the new SBTi corporate standard Version 2.0 will enter into force. It shifts focus from ambition setting to transparency and accountability. Under Version 2.0, climate targets must be formally approved by the board, progress has to be reported annually, companies have to disclose key barriers that prevented progress, and at the end of each five-year cycle, an assessment of delivery is required and must be externally assured. In our view, this will sharpen focus on delivery across all Scopes, but in particular Scope 3, as it is the trickiest category to deliver on.
Register below for the latest insights from Nordea’s Sustainable Finance Advisory team direct to your mailbox.
Read more
Cash management
As geopolitical pressures force companies to rethink their supply chains, the working capital implications are larger than many realise. You cannot redesign the physical supply chain without redesigning the financial supply chain, and treasury needs a seat at the table. Nordea’s Richard Hayes explains why in our recent Trade Trends webinar.
Read more
Explainer
Need a brush-up on the ins and outs of debt financing? Here's what you need to know.
Read more
Transaction banking
Secondary sanctions are reshaping how companies assess risk across counterparties, supply chains and financial networks. Treasury has a key role to play. Based on a Treasury Trends webinar with Richard Hayes, Chief Strategist, Transaction Banking.
Read more